Whole of life insurance is sold as a life cover product, but increasingly in the UK its role is inheritance tax planning. The nil-rate band has remained unchanged since 2009, while property values have risen significantly.
The inheritance tax nil-rate band has been frozen at £325,000 since 2009 and is now legislated to remain at that level until April 2031. The residence nil-rate band is £175,000 and is also fixed until April 2031. From 6 April 2027, most unused pension funds and pension death benefits will also be brought within the estate for Inheritance Tax purposes. HMRC estimates that around 10,500 estates will incur IHT where they otherwise would not have done, with approximately 38,500 estates paying more IHT than under the current rules. The standard Inheritance Tax rate is 40% on the taxable portion of an estate. For families with significant property, investments or pension wealth, that can create a substantial liability and a need for liquid funds to meet the tax bill. Whole-of-life cover written appropriately can be one option for providing that liquidity, but the suitability and ownership structure need to be assessed as part of wider estate planning.
| Structure | Premiums | Payout certainty | Best suited to |
|---|---|---|---|
| Guaranteed whole of life | Fixed for life, higher starting cost | Guaranteed payout on death, whenever it happens | Certainty-focused IHT or final-expense planning |
| Reviewable whole of life | Lower starting cost, reviewed periodically and can rise | Guaranteed payout, but premium is not fixed long-term | Those prioritising lower initial cost, accepting future premium risk |
| Maximum cover whole of life | Balances higher initial cover against lower long-term cost growth | Cover reduces over time relative to premium unless reviewed | Those wanting the highest cover for the lowest initial outlay |
| Term life insurance (for comparison) | Fixed, cover ends at a set date | No payout if death occurs after the term ends | Mortgage or debt cover with a clear end date, not IHT planning |
| Whole of life written in trust | Same premium structures as above | Payout is outside the estate, so it does not itself add to the IHT bill it is meant to help pay | Anyone using the policy specifically to fund an expected IHT liability |
Whole of life insurance is not something most people think about until they have to. By then, health changes may have made it significantly more expensive or unavailable. Here are four situations where the conversation should have started earlier.
A single person with an £800,000 estate and no direct descendants who qualifies for the residence nil-rate band has a combined threshold of £500,000. The remaining £300,000 is taxable at 40%, a bill of £120,000 due to HMRC before probate is granted. If the estate is mostly property, the family either sells the asset under time pressure or funds the tax with a bridging loan. A whole of life policy written in trust, sized to pay exactly that liability on death, removes both of those options from the equation.
From April 2027, unused pension funds will be brought into the value of a person’s estate for inheritance tax purposes. A pension pot of £400,000 sitting alongside an estate already near the nil-rate threshold could trigger an IHT bill that did not exist under the previous rules. 89% of UK adults are unaware of this change, per Standard Life research. The planning window is open, but it requires action before the change takes effect, not after.
Transfers between spouses are exempt from IHT, so on the first death no liability is triggered. On the second death, the full estate becomes liable above the combined nil-rate bands. If the surviving spouse also received other assets, if the property has appreciated further, or if pension assets fall in scope from 2027, the eventual bill can be substantially higher than it appeared at the time of the first death.
A life insurance policy not written in trust forms part of your estate on death. The payout meant to help your family can therefore be subject to inheritance tax, adding directly to the problem it was supposed to solve. Writing a policy in trust is typically free and can change how the payout is treated for IHT purposes without changing the cover or premium. It changes whether the policy proceeds are held within or outside your estate for IHT purposes. Many people with existing policies have never reviewed this.
Speak to an adviser to discuss your circumstances and find out how we can help.
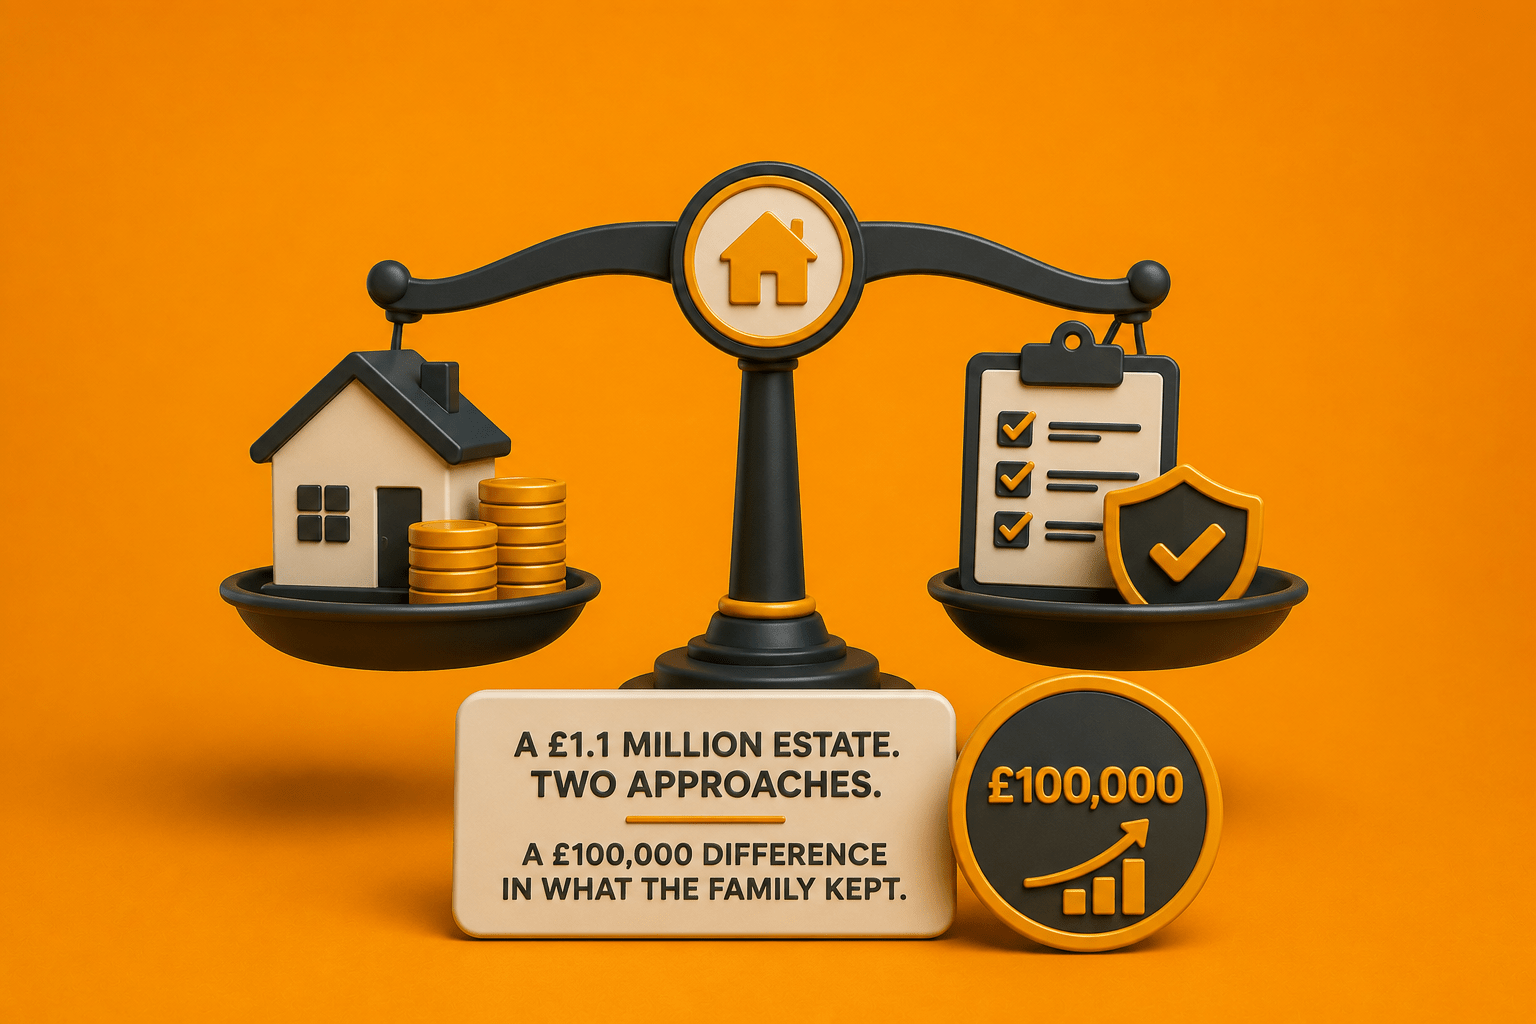
A couple’s combined estate, the family home, modest savings, and a small investment portfolio is worth £1.1 million on the second death. No inheritance tax planning was ever done because that is only for the seriously wealthy, a view that made sense in 2005 but has not kept pace with property values in southeast London. The estate exceeds the combined nil-rate bands by approximately £250,000. The IHT bill is £100,000. It is due to HMRC before probate is granted. The family home is sold in a four-month window to raise the cash. The family does not choose the buyer, the price, or the timing.
Same couple. Same estate value. A whole of life policy written in trust, so the payout sits outside the estate and is not itself subject to inheritance tax, was arranged a decade earlier when both were in their early sixties and premiums were still manageable. The policy was designed specifically to pay the anticipated IHT liability of £100,000 on the second death. That sum is paid directly to the beneficiaries from the trust, bypassing the estate entirely. The family home is not sold. Probate completes on a normal timeline. The estate passes to the next generation intact.
Clear,honest answers to the questions we hear most from clients and introducers.
The inheritance tax nil-rate band has been frozen at £325,000 since 2009 and will stay frozen until at least April 2031. The residence nil-rate band adds £175,000 for direct descendants, giving a combined threshold of £500,000 per person or £1 million for a married couple who have used both allowances. Any estate above those thresholds is taxed at 40% on the excess, due before probate is granted. Southeast London property prices have moved considerably since 2009.
A life insurance policy not written in trust falls into your estate on death and can be subject to inheritance tax above the available nil-rate bands. The payout intended to help your family can therefore increase the problem it was meant to solve. Writing a policy in trust is typically free and can change how the payout is treated for IHT purposes without changing the cover or premium. It can keep the policy proceeds outside your estate for IHT purposes. Most people with existing policies have never reviewed this.
From April 2027, unused pension funds will be included in the value of a person’s estate for inheritance tax purposes. A pension pot sitting alongside an estate already near the nil-rate threshold could trigger a liability that did not exist under the previous rules. 89% of UK adults are unaware of this change, according to Standard Life research. The window to restructure before it takes effect is open, but it requires action now.
Transfers between spouses are exempt from inheritance tax, so the first death triggers no liability. On the second death, the full estate becomes liable above the combined nil-rate bands. If the surviving spouse also inherited other assets, the property has appreciated further, or pension assets fall into scope from 2027, the eventual bill on the second death can be substantially higher than it appeared when the estate planning was last considered.
We search the market and handle the process so you can focus on moving.
Whole of market search across a wide panel of lenders
Dedicated adviser throughout the process
We handle the paperwork and liaise with lenders on your behalf
Share a few details and a member of our team will get in touch to discuss your options.
We’ll get in touch to discuss your circumstances, what you’re looking to achieve and any relevant requirements.
Based on your enquiry, we’ll explain the available options and how you can move forward.
Your enquiry will be handled confidentially, and we’ll only contact you regarding the information you’ve provided.